Buying a home in the Houston area doesn’t have to mean breaking the bank. But with affordability top of mind for buyers, knowing where to look and understanding the full cost of homeownership can make a significant difference.
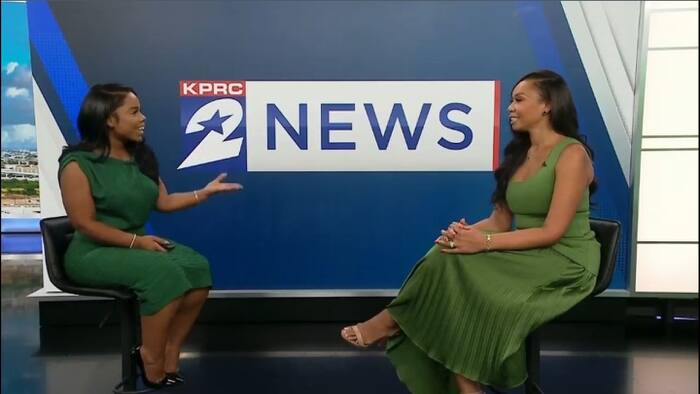
Realtor Nicole Handy with Braden Real Estate Group recently joined KPRC 2 to discuss Houston-area ZIP codes and communities where buyers may find more affordable options, along with what to consider before making a move.
Handy says Houston’s size gives buyers several options, whether they want to stay close to the city or are willing to explore communities farther out.
One area she recommends exploring is ZIP code 77028 in northeast Houston, also known as the Settegast area.
Handy said single-family homes in the area start around $200,000, while multifamily properties start in the upper $300,000s, offering options for different types of buyers.
She also pointed to the ongoing development of the Lyndon B. Johnson Hospital project as a factor to watch in the area.
Handy believes the project could help increase demand over time, potentially contributing to rising property values. However, future appreciation is never guaranteed, and buyers should evaluate each property’s condition, location and long-term costs.
For buyers willing to look beyond Houston’s core, Handy recommends exploring communities such as:
Handy said buyers may find competitive pricing in these outlying communities, sometimes comparable to options closer to the city.
However, buyers should compare individual properties and factor in commute times, transportation expenses and access to everyday services before deciding whether moving farther out makes financial sense.
Handy said one of the biggest mistakes buyers make is assuming the home with the lowest asking price is automatically the most affordable.
The purchase price is only one part of the equation. Property taxes, homeowners’ insurance, mortgage interest and other housing expenses can significantly affect a buyer’s monthly costs.
A home with a lower asking price could ultimately cost more each month than a more expensive property in an area with lower taxes or insurance costs.
That’s why Handy recommends looking beyond the listing price and calculating the total monthly cost of homeownership before making an offer.
Buyers should also consider potential maintenance expenses, homeowners association fees, if applicable, and any additional costs associated with the property.
For buyers who aren’t sure where to begin, Handy recommends working backward from a realistic monthly housing budget.
Rather than starting with a ZIP code or a home price, she suggests determining how much you can comfortably afford to spend each month.
Here’s how to get started:
1. Set a monthly housing budget.
Review your income, existing debt, savings and regular expenses to determine how much you can reasonably devote to housing without stretching your finances.
2. Talk to a mortgage lender.
A lender can help determine how much you may qualify to borrow and estimate your monthly mortgage payment. Remember that the amount you’re approved for may be higher than what comfortably fits your budget.
3. Calculate the full cost.
Ask for estimates that include principal, interest, property taxes and homeowners insurance. Depending on the property, you may also need to account for mortgage insurance, HOA fees and other expenses.
4. Work with a licensed real estate agent.
Once you understand your budget, an agent can help identify neighborhoods and properties that align with your financial goals.
5. Compare communities, not just houses.
Look at commute times, access to schools and services, transportation costs, property conditions and planned development. These factors can influence both your day-to-day expenses and your long-term satisfaction with a home.
Handy also encourages buyers not to overlook areas that are still developing or undergoing redevelopment.
These communities may offer lower entry prices than more established neighborhoods, potentially creating opportunities for buyers who plan to stay in their homes over time.
As infrastructure, businesses and services expand, demand for housing may increase. That could support property values and help homeowners build equity.
But there are no guarantees. Development timelines can change, and property values can rise or fall depending on market conditions.
Before buying in a developing area, research planned projects, verify their current status and consider whether the property makes sense financially even if appreciation takes longer than expected.
For Houston-area buyers, finding an affordable home starts with understanding what they can comfortably afford each month then identifying the neighborhoods that fit that budget.
Handy’s advice: Don’t limit your search to the most familiar neighborhoods, and don’t judge affordability by the listing price alone.
Whether you’re considering northeast Houston, Crosby, Baytown, Fulshear or another Greater Houston community, comparing total housing costs and researching the area can help you make a more informed decision.
The goal isn’t simply to find the cheapest home. It’s to find a home that fits your budget today and your financial goals for the future.


